Key Takeaways
- Understanding advisor compensation helps you make informed retirement planning decisions as a federal employee.
- Both fee-only and commission-based advisors offer unique benefits—evaluate based on transparency, cost, and alignment with your needs.
Are you weighing fee-only against commission-based federal financial advisors? How your advisor is compensated can directly influence your retirement planning, especially when navigating federal benefits. This Q&A will clarify each advisor type, address differences, and empower you to make confident decisions about your Thrift Savings Plan and future.
What Is a Fee-Only Financial Advisor?
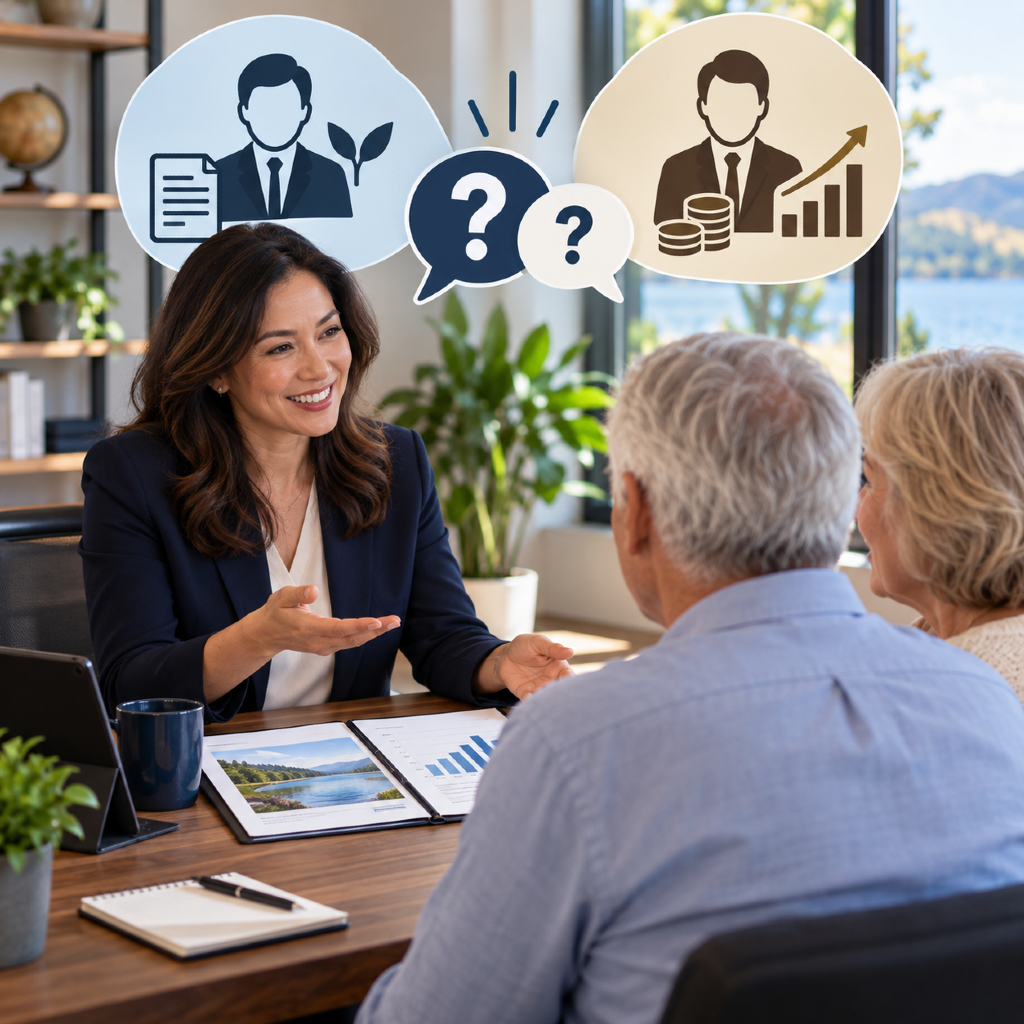
Fee-only financial advisors are compensated exclusively through fees paid by you, not commissions from products or services. They provide guidance that focuses on education and the unique needs of federal employees.
How Fee-Only Advisors Are Compensated
Fee-only advisors earn their income from flat fees, hourly rates, or a percentage of assets under management. They do not receive commissions from product sales, allowing them to prioritize your financial situation without incentive to recommend a particular product. Their compensation method creates transparency and can reduce potential conflicts of interest.
Common Services Provided to Federal Employees
For federal employees, fee-only advisors often:
- Assist in understanding federal retirement systems and benefits
- Guide you through Thrift Savings Plan (TSP) allocations and rollovers
- Educate about health, pension, and survivor benefits
- Develop comprehensive retirement transition plans
Their approach prioritizes objective education designed for federal service circumstances.
What Does Commission-Based Mean?
Commission-based advisors are compensated largely through commissions from the sale of financial products or services. They may receive compensation when you purchase certain mutual funds, insurance policies, or investment products.
How Commission Advisors Earn Income
These advisors earn a portion of the product’s sale price as a commission. Their compensation varies depending on the product type and can come from one-time transactions or ongoing arrangements, such as recurring commissions on specific products. Their income is closely linked to the financial solutions they recommend.
Services Commission Advisors Offer Retirees
To retirees and pre-retirees, commission-based advisors commonly:
- Present investment and insurance options for retirement income
- Suggest annuities, long-term care solutions, or life insurance products
- Help manage legacy planning tools within federal benefits structures
While these services can be helpful, the compensation link to product sales means it’s important to ask how your advisor is paid.
Key Differences Between Fee-Only and Commission
Understanding these two models helps you evaluate your choices and maintain your retirement strategy’s integrity.
Compensation Structures Explained
Fee-only compensation comes directly and transparently from you via agreed-upon charges—either a flat fee, an hourly rate, or as a percentage of assets under management. Commission structures, on the other hand, tie advisor earnings to products sold to you. Some advisors may use hybrid models, so be sure to clarify how your prospective advisor is compensated.
Potential Conflicts of Interest
A major distinction is the potential for conflicts of interest. Fee-only advisors are less likely to be influenced by sales incentives, while commission-based models may introduce bias toward recommending certain products. Understanding these dynamics helps you choose advice best aligned with your goals, especially when significant retirement choices are at stake.
What Should Federal Employees Consider?
Your federal benefits are unique and deserve tailored guidance. Here’s how advisor compensation models may affect your retirement planning.
Impact on Retirement Planning Decisions
The advisor’s compensation impacts the recommendations you receive. Fee-only advisors tend to focus on holistic planning, while commission-based advisors may emphasize certain investment or insurance solutions. Consider whether you want education-driven support or recommendations where product sales play a role.
Considerations for Thrift Savings Plan Choices
The TSP is central to your retirement savings. Fee-only advisors generally provide unbiased comparisons between TSP options and private accounts. Commissioned advisors may introduce outside investment solutions. Ask how any recommendation will specifically enhance—rather than complicate—your existing federal benefits.
Pros and Cons of Each Approach
No model is one-size-fits-all. Both offer different strengths and considerations, especially in the context of federal retirement.
Advantages of Fee-Only Advisors
- Transparency: You know exactly what you’re paying for advice and services.
- Objectivity: With no product sales incentives, recommendations are more aligned with your long-term interests.
- Focus: Advisors concentrate on education and personalized financial plans for federal employees.
Drawbacks of Commission-Based Models
- Potential Bias: Recommendations may skew toward commission-generating products, not always in your best interest.
- Less Clarity: Compensation details may be less transparent, making it harder to compare costs.
- Complexity: Some products may feature costs and features that are not immediately apparent and may affect your federal benefits integration.
Which Advisor Model Fits Your Situation?
Choosing the right advisor depends on your preferences for transparency, education, and the support you want throughout retirement.
Questions to Ask Before Choosing
- How are you compensated for your services?
- Do you have experience with federal retirement systems?
- Can you explain how your recommended solutions integrate with my Thrift Savings Plan and federal benefits?
- Are you required to act in my best interest at all times?
These questions encourage open discussion and help you evaluate whether an advisor’s approach suits your needs.
How to Evaluate Financial Services Providers
- Review Credentials: Look for advisors with experience advising federal employees or retirees.
- Consider Independence: Fee-only professionals typically operate independently. Commission-based advisors might be tied to certain product offerings.
- Evaluate Communication: How clearly does your advisor explain complex topics? A good advisor prioritizes education over persuasion.
- Ask for a Clear Fee Schedule: Transparency in fees and potential commissions ensures you understand the cost of guidance.
Can You Change Advisor Types Later?
Yes, you can change how you receive financial guidance as your needs evolve or if you feel a different model is warranted.
Making Adjustments to Your Retirement Team
If your confidence in your advisor model changes, you can interview and select a new financial services provider. Review your goals, current benefits, and desired level of education or support. Transitioning from a commission-based advisor to a fee-only advisor—or vice versa—may require updating account authorizations, reviewing ongoing service agreements, and clarifying how new guidance fits with your retirement timeline.
FAQ: Understanding Advisor Compensation
Do Fees Affect Retirement Outcomes?
Fees and commissions can impact your retirement savings by affecting your net returns or access to certain solutions. Understanding all expenses—advisory fees or commissions—is essential for sound retirement planning.
What Else Should You Know?
No advisor model is perfect for everyone. Consistently ask for transparency, prioritize ongoing education, and periodically reassess your advisor relationship. Staying proactive ensures your retirement team always aligns with your evolving federal benefits and long-term goals.