Key Takeaways
- Understanding how FEHB and Medicare Part B work together empowers you to make informed healthcare decisions in retirement.
- Recent policy changes have impacted coordination strategies, making it crucial to stay updated for optimal benefit management.
Navigating your federal retiree health benefits can be confusing, especially when it comes to integrating FEHB coverage with Medicare Part B. With persistent myths and ongoing policy updates, knowing the facts helps you make sound choices about your healthcare in retirement.
What Is FEHB and Medicare Part B?
Overview of FEHB Benefits
- Also Read: VERA Early Retirement Eligibility vs Normal Federal: Key Trade-Offs Explained
- Also Read: Case Study: Correcting Service Record Errors and Their Impact on Retirement
- Also Read: Social Security Timing for Federal Employees: Claim Age Rules and Key Changes
Understanding Medicare Part B Coverage
Medicare Part B is a part of the national health insurance program for those aged 65 and older or qualified by disability. Part B specifically covers outpatient services like doctor appointments, lab work, preventive screenings, and durable medical equipment. Enrollment is typically voluntary, with monthly premiums adjusted based on your income.
How Federal Retirees Are Eligible
Once you retire from federal service, reaching age 65 generally makes you eligible for Medicare. As a retiree, you can keep your FEHB plan and choose whether or not to enroll in Medicare Part B. Coordinating these options is a unique aspect of the federal benefits landscape.
Why Do Federal Retirees Coordinate Coverage?
Goals of Coordination
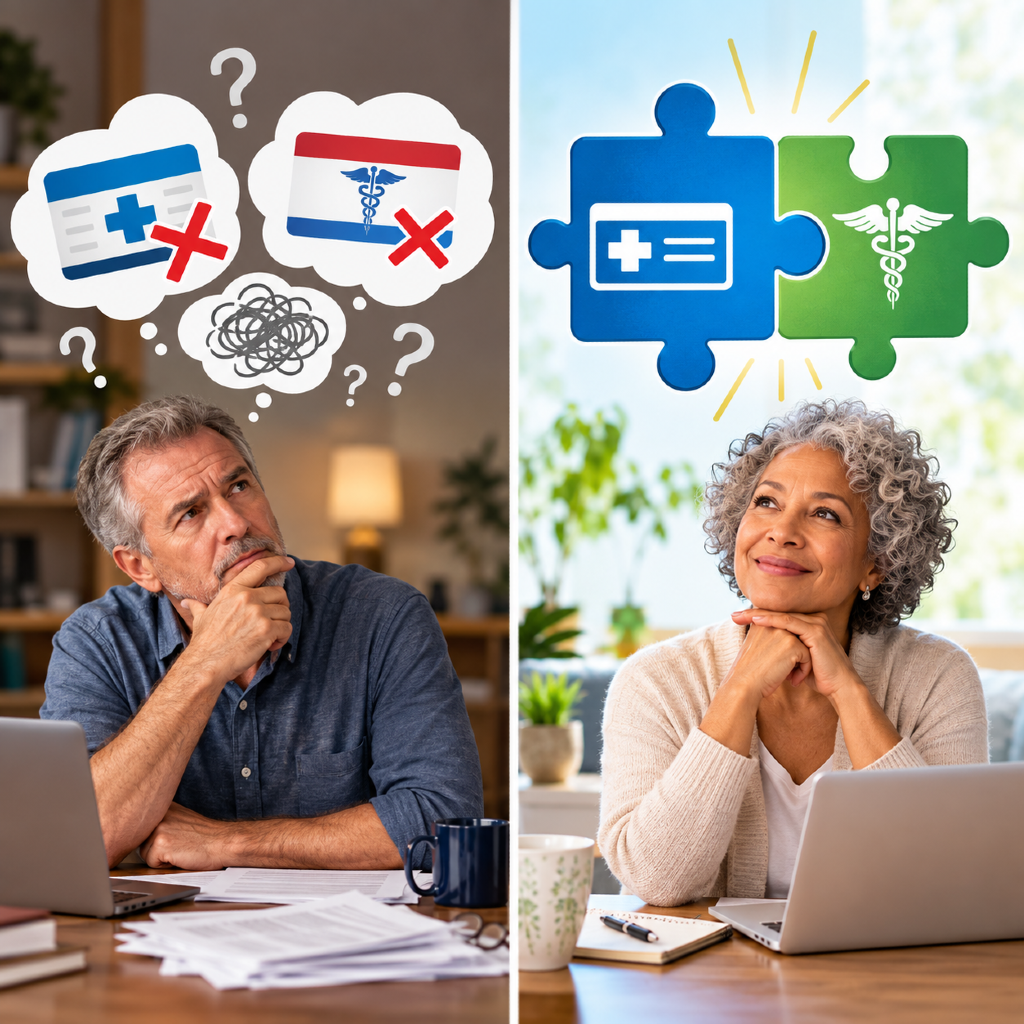
Coordinating FEHB with Medicare Part B allows you to limit out-of-pocket expenses and broaden your access to care. The goal is to create a seamless healthcare safety net in retirement, maximizing quality and minimizing coverage gaps.
Common Concerns for Retirees
Many retirees wonder if they should enroll in both FEHB and Part B, if dropping FEHB is wise, or whether one plan will serve as a backup for the other. Questions about potential penalties, automatic enrollments, and overall cost are top of mind.
Financial and Healthcare Considerations
Making this choice means weighing the cost of premiums against possible savings on deductibles, copays, and coinsurance. It also involves considering provider choice, medical needs, and family coverage. Ultimately, your coordination strategy should reflect both your health status and your long-term financial wellbeing.
What Are the Biggest FEHB + Medicare Myths?
Top Misconceptions Explained
Several myths circulate within the federal retiree community. Some believe enrolling in Part B is mandatory or that keeping both plans is redundant. Others think FEHB will cover all needs regardless of Medicare, or that Medicare automatically cancels FEHB. These misconceptions often lead to unnecessary costs or missed benefits.
How Misinformation Spreads
In-person discussions, online forums, and outdated reference materials all contribute to confusion. Benefits are personal, but well-intentioned advice from colleagues doesn’t always consider recent regulatory changes or your unique circumstances.
Verifying Reliable Sources
Trustworthy information comes from official resources such as OPM, the Social Security Administration, and Centers for Medicare & Medicaid Services (CMS). Regularly review updates from these agencies or seek guidance from certified financial services professionals specializing in federal retiree benefits for accurate, up-to-date advice.
How Does Coordination Actually Work?
Primary vs Secondary Payer Rules
When you’re enrolled in both FEHB and Medicare Part B, at age 65 or older, Medicare typically pays first (primary), and FEHB pays second (secondary). This order can reduce your out-of-pocket liability. If you only have FEHB, it pays as primary. Knowing the payer order is essential for planning your coverage use and understanding claims processes.
Enrollment Timing and SEPs
You have a seven-month initial enrollment period for Medicare Part B, starting three months before the month you turn 65 and ending three months after. Delaying enrollment without other credible coverage may lead to late enrollment penalties. However, FEHB is considered credible coverage, and special enrollment periods (SEPs) may apply if you’re covered by FEHB due to current employment.
Effects on Out-of-Pocket Costs
By enrolling in both, many retirees see reductions in copays and deductibles—since the plans coordinate benefits. However, you’ll pay premiums for both programs. Deciding whether the out-of-pocket savings and provider flexibility offset the extra expense depends on your individual health and usage patterns.
Which Options Offer the Most Flexibility?
Pros and Cons of Staying with FEHB Only
If you choose to continue with only FEHB, you avoid the extra premium for Medicare Part B. However, you may pay higher out-of-pocket costs for certain services, and some providers may require Medicare. For those in generally good health, or who need family coverage, this option may remain appealing.
Pros and Cons of Adding Medicare Part B
Enrolling in both FEHB and Part B often leads to broader provider access and lower copays. Many FEHB plans waive some cost-sharing for enrollees who have Medicare Part B, reducing your potential out-of-pocket burden. The main drawback is the added monthly cost for Part B premiums.
Switching or Suspending FEHB
Some retirees explore suspending FEHB to enroll in another Medicare option, like a Medicare Advantage plan. Suspension (rather than cancellation) preserves future FEHB eligibility if needs change. But careful evaluation is needed—returning to FEHB is only possible under certain circumstances, and benefits may differ between programs.
How Has Coordination Changed Since 2025?
Recent Policy Updates
Since 2025, several updates have improved coordination between FEHB and Medicare. Enhanced integration means better coverage for overlapping services and more transparency about what’s covered by each payer. Some FEHB plans have also revised their cost-sharing structures to reflect the presence of Medicare as primary coverage.
Impacts of Windfall Elimination Provision Repeal
With the Windfall Elimination Provision (WEP) repealed in 2025, federal retirees under FERS no longer see reductions to their Social Security benefits due to government service. This change doesn’t directly impact FEHB or Medicare coordination, but it may enhance your overall retirement income, possibly influencing how you prioritize and budget for healthcare options.
What Retirees Should Monitor
Policy changes may continue, affecting premiums, benefits, and provider networks. Staying informed about legislative updates, OPM guidance, and plan documentation remains essential to maximizing your healthcare strategy in retirement.
What Common Questions Do Retirees Have?
Enrollment Deadlines
Missing Medicare Part B enrollment deadlines can lead to penalties or gaps in coverage. Mark your calendar for key milestones such as your initial eligibility at age 65, and review OPM communications during open seasons to evaluate your FEHB options.
Cost Management Tips
To keep healthcare costs manageable, regularly review your coverage needs, examine plan brochures, and assess how your health status may change. Use online calculators and official resources to compare premium, deductible, and copay structures yearly.
Where to Find More Information
Reliable, up-to-date details are available at official sites like OPM.gov and Medicare.gov. Consider attending government-hosted webinars or consulting with financial services professionals specializing in federal retiree benefits for personalized, compliance-safe education tailored to your situation.