Key Takeaways
- Understanding RMD rules helps you stay compliant and avoid costly penalties in retirement.
- Federal retirement accounts have unique RMD deadlines and considerations compared to private sector plans.
Most federal retirees will face required minimum distributions (RMDs) from their retirement accounts. While the process may sound straightforward, the rules and deadlines can be complex—especially for federal employees. This article breaks down everything you need to know about RMDs, so you can plan ahead and stay compliant in 2026 and beyond.
What Are RMDs for Federal Retirees?
Definition of Required Minimum Distributions
- Also Read: Case Study: RMD Tax Planning Strategies for Federal Retirees and Taxes
- Also Read: Best Social Security Strategy for Federal Employees: Timing and Claiming Options
- Also Read: Buying Years of Service—Does It Pay? Key Impacts for Federal Retirement
Federal Retirement Accounts Affected
If you’ve worked for the federal government, RMD requirements apply to several account types:
- Thrift Savings Plan (TSP)
- Traditional IRAs
- Certain 403(b) and 401(k) plans, if you have these from federal service
- Other qualified employer plans you may have participated in
Roth IRAs are exempt from lifetime RMDs for original account holders, but inherited Roth accounts may have different requirements.
Why Do RMD Rules Matter?
IRS Requirements for Distributions
The IRS requires you to begin taking RMDs by April 1 of the year after you reach the applicable starting age. For most retirees in 2026, this age is now 73. Each year after, you must withdraw your annual RMD by December 31.
Potential Tax Implications
Missing an RMD can have significant financial consequences. If you miss your deadline, the IRS imposes a penalty tax—currently 25% of the amount you failed to withdraw. Additionally, RMDs are generally considered ordinary income, which could affect your tax bracket, Social Security taxation, or Medicare premium levels.
How Do Federal and Private RMDs Differ?
Comparison of Federal and Private Plans
While both federal and private-sector retirement plans must follow IRS guidelines on RMDs, they differ in how accounts are administered. Federal retirees typically manage funds through the TSP, which has its own set of distribution rules and processes. Private sector plans, such as 401(k)s and standard IRAs, may offer more withdrawal flexibility or different investment choices, but the core RMD regulations remain the same.
Unique Federal Retirement Considerations
Federal employees often have a combination of retirement assets, such as the TSP and FERS or CSRS annuities. While TSP and similar accounts are subject to RMDs, federal pensions themselves are not. It’s important to understand how these accounts interact and coordinate withdrawals to minimize tax implications and maintain income consistency.
What Are Current RMD Deadlines?
Key Dates for Federal Retirees
For most federal retirees, your first RMD must be taken by April 1 following the year you reach age 73. After the first year, RMDs are due by December 31 annually. If you delay your first RMD until April of the following year, you will be required to take two distributions in one calendar year, which could affect your taxable income.
Late RMD Penalties Explained
Missing an RMD deadline is costly. The IRS can assess a penalty equal to 25% of the amount not distributed as required. If you realize you missed an RMD, you can file IRS Form 5329 and request a waiver, but it isn’t guaranteed. Staying ahead of RMD deadlines is essential for all federal retirees.
Common Questions About RMD Planning
How Can You Prepare for RMDs?
Start by inventorying all retirement accounts subject to RMDs. Work with your retirement services provider to calculate each year’s required withdrawal. Review your withdrawal strategy to avoid unnecessary tax spikes, considering how RMDs integrate with pensions, Social Security, and non-retirement funds.
Who Is Required to Take RMDs?
Anyone with a traditional IRA, TSP, or similar tax-deferred retirement account must take RMDs starting at age 73 (unless new legislation updates the age in future years). If you’re still employed by the federal government after this age and do not own more than 5% of your employer, you may be able to delay RMDs from your current plan but not from IRAs or former employer plans.
Non-Typical RMD Scenarios for Federal Employees
Inherited Accounts and RMDs
If you inherit a federal retirement account or IRA, specific RMD rules apply. Non-spouse beneficiaries are typically subject to the “10-year rule,” which requires account depletion within a decade, though some exceptions exist. Spouses have more flexibility, such as treating the account as their own or stretching distributions.
RMDs When Returning to Federal Service
If you return to federal employment after starting RMDs, you may be able to pause RMDs from your TSP if you remain employed. However, you still must take RMDs from IRAs and accounts from prior employers. This highlights the importance of reviewing your personal circumstances each year.
Recommended RMD Planning Strategies
Coordinating Withdrawals with Tax Planning
RMDs are not just about compliance—they also provide an opportunity to manage your overall income and tax liability. Consider coordinating withdrawals from traditional and Roth accounts to smooth your taxable income over several years. Factor in other income streams when planning withdrawals to prevent sudden jumps in your tax bracket.
Staying Compliant with Federal Rules
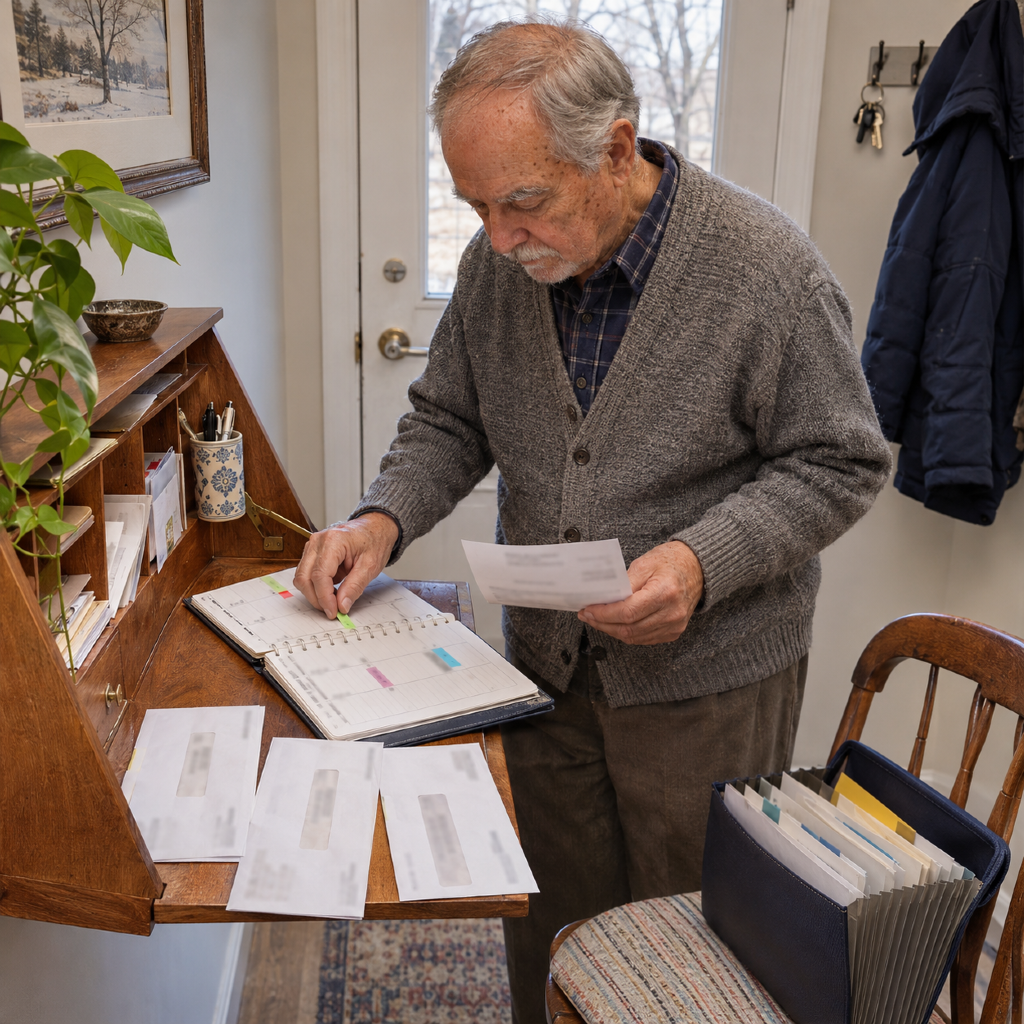
Maintain a checklist of key RMD dates and amounts for each account. Pay particular attention to TSP processes, which may differ in terms of distribution forms or timing. Keep thorough documentation, and don’t hesitate to consult with a qualified professional for annual reviews to remain compliant with evolving federal rules.
Taking time to understand and plan for RMDs can help you avoid penalties and maintain a stable financial foundation throughout retirement. Remember, compliance is key, and a strategic approach pays off when navigating federal retirement rules.