Key Takeaways
- Pension and TSP advisors provide crucial, factual guidance and education to help you avoid common retirement misconceptions.
- Staying informed about federal benefits empowers you to make confident decisions, maximizing your long-term retirement security.
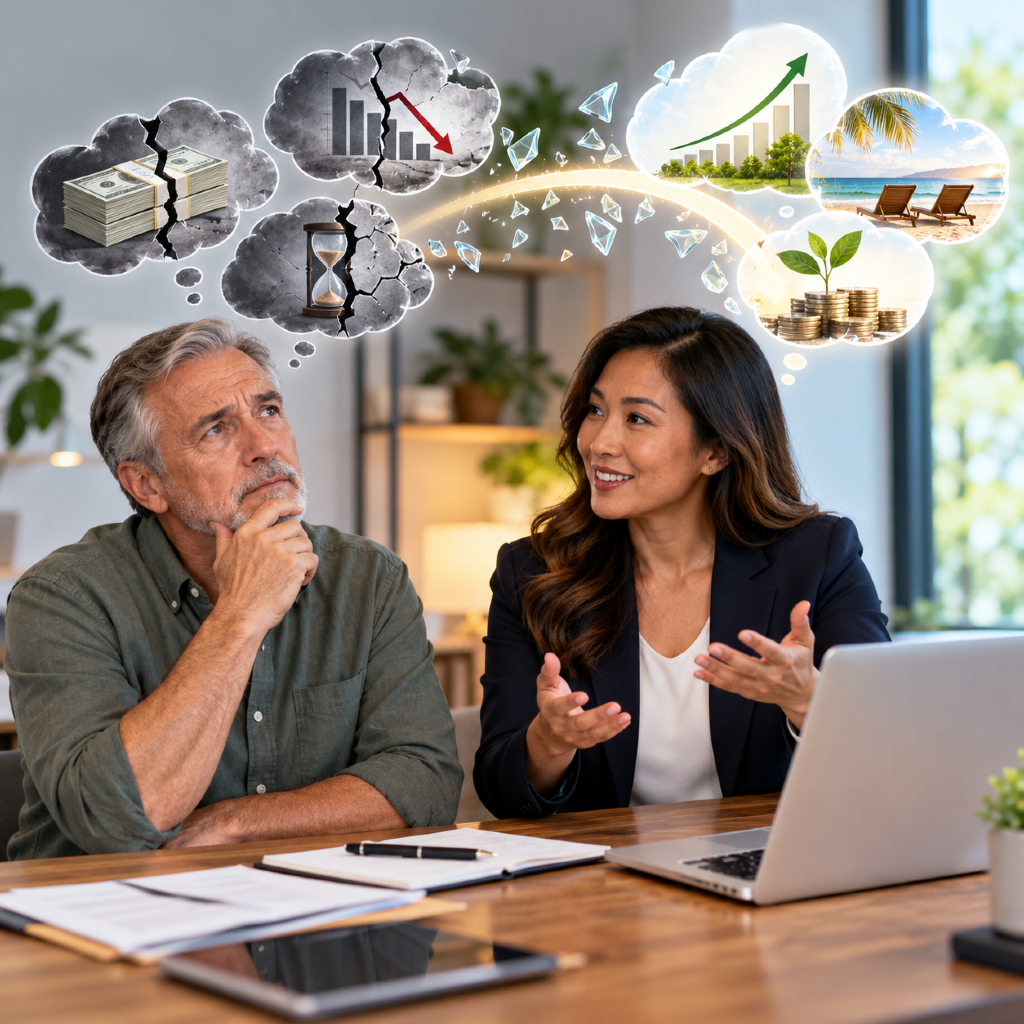
If you’re a federal employee or retiree sorting through the maze of retirement options, you’ve probably heard some persistent myths about your pension and Thrift Savings Plan (TSP). In this case study, you’ll see how a specialized advisor can help you separate fact from fiction and build a secure, informed retirement plan.
What Is a Pension and TSP Advisor?
Advisor role in retirement planning
- Also Read: Annuity Options Explained: Pros and Cons for Federal and Postal Retirees
- Also Read: Disability Retirement Myths and Facts: Insights for Federal and USPS Employees
- Also Read: Accidental Death and Dismemberment Nuances: Myths vs Facts for Federal Retirees
Services for federal employees
Federal employees have unique needs, given the complexity of benefits like the Federal Employees Retirement System (FERS), Civil Service Retirement System (CSRS), and TSP options. Advisors trained in this field provide broad educational services: explaining how benefits coordinate, outlining timelines for key decisions, and helping you understand factors like healthcare, survivor benefits, and Social Security’s place in your overall plan.
Why Do Retirement Myths Persist?
Origins of common misconceptions
Many retirement myths start with simple misunderstandings. Maybe a friend shared an anecdote at work, or maybe an outdated article made the rounds on email. Changes in law can also create confusion that lingers for years. For federal employees, language differences between civilian and federal retirement programs, plus evolving rules, mean that even simple statements get twisted or misunderstood.
Impact on retirement decisions
If you hold onto the wrong information, you might overestimate what your pension covers or underestimate TSP risks. This can lead to financial shortfalls or missed opportunities. Advisors often find that clients delay retirement, cash out benefits early, or invest too conservatively—all based on misinformed beliefs. Dispelling these myths early can help you avoid costly missteps.
Can Advisors Really Debunk These Myths?
Advisor expertise in federal benefits
Specialized advisors stay current on every update impacting FERS, CSRS, TSP rules, and Social Security integration. By focusing exclusively on federal retirement, they bring clarity to otherwise confusing topics. They don’t offer guarantees or projections; instead, they break down policies and options so you can confidently choose what works for you.
Educational approach to myths
Rather than simply refuting misinformation, effective advisors guide you through the reasoning process—showing paperwork, walking through calculations, and illustrating outcomes. This approach builds your awareness and educates you so you can spot misleading advice on your own. Good advisors focus on long-term learning, not one-time consultations.
Myth 1: TSP Accounts Are Risk-Free
Understanding TSP investment options
A common myth is that your TSP is entirely safe from market ups and downs. However, like any retirement account, the TSP offers both conservative (G Fund) and more volatile (C, S, I Funds) options. While the G Fund provides principal protection, the other funds follow the broader bond and equity markets, which involve risk of loss and opportunity for growth.
Managing risk effectively
Your TSP balance will fluctuate based on your investment choices. An advisor will help you understand this risk and diversify according to your retirement timeline and comfort level, emphasizing education about how allocations affect both growth and principal security. Understanding your options is far more effective than relying on “safe” myths.
Myth 2: Pensions Guarantee Full Retirement
How pension calculations work
A federal pension, whether through FERS or CSRS, is calculated based on your years of service and salary history. While it forms a solid retirement foundation, the benefit generally covers only a portion—not 100%—of your pre-retirement income. Misunderstanding the formula or eligibility requirements often leads to the false belief that a pension alone will fully fund your lifestyle in retirement.
Factors affecting pension income
Key variables include your retirement age, length of government service, any previous military credit bought back, and the option of survivor benefits or reductions for early retirement. Cost-of-living adjustments can help keep pace with inflation, but pensions do not automatically guarantee a seamless transition to your working salary in retirement. Advisors help you see the big picture so your expectations are realistic.
Myth 3: Social Security Replaces Most Income
Social Security basics for federal workers
Social Security is a valuable resource for federal retirees, but it rarely replaces the majority of your pre-retirement income. For FERS employees, Social Security supplementation is designed to coordinate with your pension and TSP withdrawals. The benefit amount depends on your earnings history and when you claim, and it should be viewed as one piece of a multi-source retirement income plan.
The repeal of the Windfall Elimination Provision
As of 2025, federal employees under FERS are no longer impacted by the Windfall Elimination Provision (WEP). This means your earned Social Security benefits are paid out in full based on your credited earnings, removing a previous source of confusion and concern about potential reductions. Advisors now emphasize the importance of incorporating Social Security without the complexity of earlier offset provisions.
Are There Hidden Pitfalls in Retirement Planning?
Healthcare costs after retirement
One area often underestimated is the out-of-pocket costs for healthcare after federal employment ends. While federal retirees can continue coverage through the Federal Employees Health Benefits (FEHB) Program, premiums and uncovered expenses may rise. Advisors help you factor these into your broad retirement budget so you’re not caught off guard.
Inflation and purchasing power
Inflation can quietly erode fixed-income streams over time. Even with cost-of-living adjustments, your pension and Social Security may not always keep pace with rising prices. Advisors illustrate scenarios so you understand the value of maintaining some growth potential in your TSP and other accounts, balancing safety with the need to preserve purchasing power.
What Can You Learn From This Case?
Key takeaways for federal retirees
First, education is your strongest tool. Myths thrive when information is scarce or out of date. Second, each element of your retirement—pension, TSP, Social Security, and health coverage—serves a unique role. Effective planning means understanding how these sources interact and making decisions with a clear, factual basis.
Steps to build retirement awareness
Start by reviewing official resources (such as OPM or TSP.gov) regularly. Engage with advisors who demonstrate expertise in federal benefits and educational priorities. Attend informational sessions, ask questions, and revisit your plan annually as rules and personal circumstances change. Awareness and proactivity are the best safeguards against retirement pitfalls.