Key Takeaways
- Many federal retirees misunderstand what AD&D coverage includes and its limitations.
- Accurate knowledge helps you make informed decisions about your retirement security.
Many federal retirees are surprised to learn that some widely held beliefs about accidental death and dismemberment (AD&D) insurance do not reflect how these policies actually work. Understanding the specifics of AD&D can help you make informed decisions about your protections in retirement.
What Is Accidental Death and Dismemberment?
Basic Definition and Coverage
- Also Read: Disability Retirement Myths and Facts: Insights for Federal and USPS Employees
- Also Read: Case Study: How a Pension and TSP Financial Advisor Debunks Common Myths
- Also Read: TSP Allocation Strategy Trends: Key Factors for Federal Employees in 2026
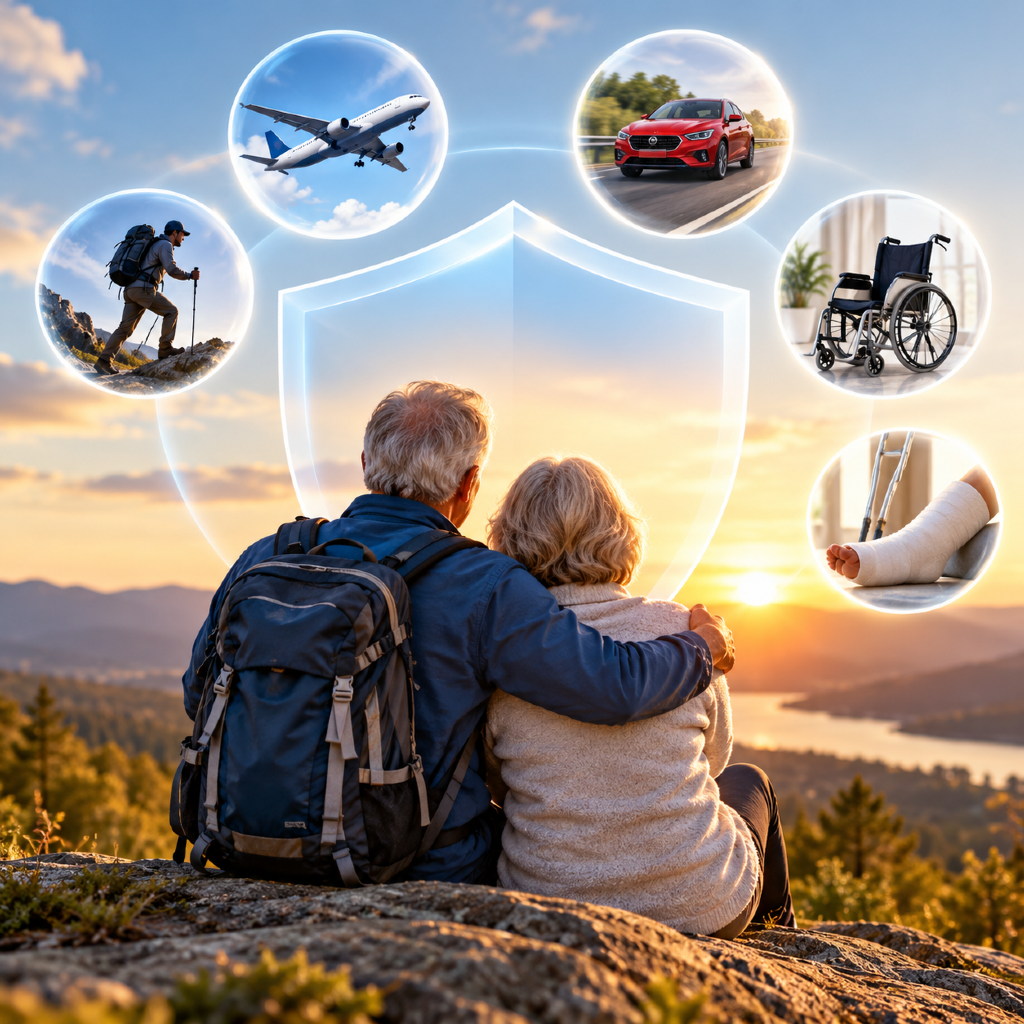
AD&D is not comprehensive health or life insurance; its scope is narrower. Coverage pays only for events that happen as a direct result of accidents, rather than illness, natural causes, or age-related decline. Typically, you or your beneficiaries can claim benefits only for incidents that meet the policy’s definition of an “accident.”
How It Differs From Life Insurance
A common source of confusion is how AD&D is different from standard life insurance. Life insurance generally pays a benefit to your named beneficiaries if you pass away from almost any cause, including illness or natural causes (subject to policy terms). In contrast, AD&D will only pay if your death or qualifying injury results directly from a covered accident. If you pass away due to illness or other non-accidental causes, AD&D coverage will not pay a benefit.
Why Do Federal Retirees Consider This Coverage?
Common Scenarios for Federal Retirees
As you transition into retirement, you may focus on protecting your loved ones and ensuring financial stability. Many federal retirees consider AD&D coverage because it provides an added layer of protection for unexpected, accidental events. For individuals who travel frequently, remain physically active, or want additional peace of mind, AD&D may seem like a relevant choice.
Additionally, retirees sometimes look for supplementary coverage to close any gaps left by traditional life insurance plans, especially if they believe accidental injuries could threaten their financial goals. Understanding the situations where AD&D applies can help you decide whether it fits your circumstances.
Retirement Planning Considerations
When you’re planning for retirement, it is important to analyze your overall protection strategies. Federal retirees might examine whether AD&D complements their existing benefits, such as those provided through the Federal Employees Retirement System (FERS) or Civil Service Retirement System (CSRS).
It’s also worth understanding that AD&D is not a substitute for health, disability, or comprehensive life insurance. Instead, it should be weighed as a component of a broader risk management approach for you and your dependents.
What Myths Are Most Common?
Myth: All Deaths Are Covered
One prevalent myth is that all deaths are covered under AD&D. In reality, AD&D policies only pay out in very specific, accidental circumstances. Deaths caused by illness, natural aging, suicide, or other non-accidental events are generally excluded. Reading your policy’s definitions and exclusions carefully is crucial.
Myth: Benefits Last for Life
Another misconception is that AD&D benefits automatically last for life regardless of eligibility or enrollment status. In many instances, AD&D coverage may end upon separation from federal service, or upon reaching a certain age, unless you actively re-enroll or maintain coverage through retirement. It’s important to check enrollment requirements and renewals as part of your retirement planning.
Myth: Coverage Is Automatic With Retirement
Some assume that once they retire from federal service, AD&D coverage continues seamlessly or is automatic. In fact, most AD&D options require participants to actively elect continuation or enroll in a retiree-specific option. Review your benefits paperwork and consult a retirement counselor to avoid gaps in protection.
What Are the Key Facts Federal Retirees Should Know?
Eligibility and Enrollment Details
After you retire, eligibility for AD&D coverage depends on your plan and specific federal benefit programs. Not all AD&D policies continue past active employment. You may need to take action to enroll in retiree coverage or continue existing coverage during open seasons or separation processes. Certain plans may have age restrictions, waiting periods, or other eligibility criteria important to note.
Benefit Limitations for Federal Retirees
While some benefits of AD&D coverage carry over into retirement, the amount and duration of coverage may be limited. Maximum benefit amounts or payout terms might change upon retirement or after reaching certain age milestones. There may also be exclusions for high-risk activities, travel, or injuries sustained under specific circumstances. Always read your plan documents carefully to understand limitations as a retiree.
Integration With Other Federal Benefits
AD&D is usually positioned as a supplement to traditional retirement offerings. It does not replace your federal pension, Social Security, or other core post-retirement benefits. Instead, it can potentially provide an extra payout in the event of accidental injury or death, working alongside other components of your benefits package. Be aware that in some cases, other insurances or policies may impact your eligibility or the amount of benefits received from AD&D.
How Does This Coverage Work in Practice?
Claim Process Overview
Filing a claim for AD&D coverage generally involves notifying the plan administrator, submitting proof of the accident, and providing supporting documentation like medical records or accident reports. The administrator will review eligibility, confirm accident details, and determine if the circumstances meet policy definitions.
Timely communication and thorough documentation help ensure that claims are processed efficiently. If your claim is denied, you usually have the right to appeal—review the appeals process in your policy materials to fully understand your options.
Coordinating With Federal Benefits
When you receive federal retirement benefits, filing an AD&D claim might overlap with other benefits. For example, you may need to coordinate with life insurance benefits provided through the Federal Employees’ Group Life Insurance (FEGLI) program or other optional insurances. It’s wise to keep records of all your coverage and communicate with your benefits office to avoid delays or conflicts.
Who Might Not Need This Coverage?
Alternative Protection Options
If you have strong life insurance, comprehensive health coverage, or substantial personal savings, you might consider whether AD&D adds real value for you. Some individuals instead focus on maximizing their core federal benefits or purchasing long-term care protection.
Evaluating Individual Circumstances
Consider your health status, lifestyle, and family responsibilities when deciding if AD&D is appropriate. If your risk of accidental injury is low and you have existing policies in place, additional coverage may not provide meaningful benefits. A careful evaluation of all assets, insurance, and needs helps you make an informed choice for your retirement peace of mind.